
ROHINI GUPTA v. DISTRICT DEPUTY REGISTRAR: A CRITICAL LEGAL ANALYSIS OF THE SCOPE AND LIMITS OF DEEMED CONVEYANCE UNDER SECTION 11 OF MOFA
ROHINI GUPTA: CRITICAL LEGAL ANALYSIS AND FALLACIES The following analysis identifies potential issues in the reasoning of Rohini Gupta by comparing the judgment with the principles discussed in Ivory Properties, A.H. Wadia Trust and the other decisions referred to in the draft. The points below are arguable grounds for examination; they should not be treated as established findings of error without verification against the complete judgments and underlying documents. 1. Rohini Gupta v. District Deputy Registrar Bombay High Court | 8 September 2026 | Writ Petition No. 5991 of 2026 | Justice Sandeep V. Marne The judgment dismissed the original landowners’ writ petition and upheld the deemed conveyance of 3,901.70 sq. m. of land to the society. The principal issue is whether the Court correctly moved from its finding that the landowners were promoters to the conclusion that they were obliged to convey their reversionary ownership of the land. 2. The principal legal conflict The central issue is that Rohini Gupta recognises the principle that deemed conveyance cannot ordinarily exceed the promoter’s rights, but nevertheless upholds freehold conveyance on the particular facts before the Court. The comparison requires distinguishing between an error in interpreting Section 11 of MOFA, an error in appreciating the lease deed and registered agreements, and an error in exercising the competent authority’s jurisdiction. A different conclusion on the facts does not, by itself, establish an error of law. Legal issue Earlier legal position Rohini Gupta judgment Extent of rights under Section 11 Society ordinarily receives the rights the promoter is entitled and obliged to convey. The Court held that the landowners were also promoters and were obliged to convey their ownership interest. Leasehold versus freehold An authority cannot ordinarily substitute freehold ownership for an agreement expressly limited to leasehold rights. The Court upheld freehold conveyance, relying on the landowners’ participation in the project and the agreements concerning ownership. Effect of an existing lease assignment An assignment may fulfil the promoter’s obligation to transfer the leasehold interest. The Court held that the earlier assignment fulfilled only part of the statutory obligation because the landowners had a separate obligation. Jurisdiction under Section 11 Deemed conveyance requires failure to fulfil the statutory obligation. The Court found a continuing failure on the part of the landowners, notwithstanding the earlier assignment. Nature of proceedings Summary proceedings do not finally determine complicated title disputes. The Court upheld the order while preserving the parties’ right to pursue appropriate civil proceedings. The judgment relies on A.H. Wadia Trust, Haresh Vijaysinh Bhatia and other decisions to distinguish cases where the promoter is merely a lessee from cases where the landowner is also a promoter or has an independent statutory obligation to convey. 3. Possible errors in Rohini Gupta judgment The following are potential grounds for challenging the reasoning. They are arguable errors, not findings that the judgment is necessarily erroneous. Sr. No. Paragraph of Rohini Gupta Possible error in reasoning Legal significance 1 Paras 14–15, 21–24 Treating participation in construction as sufficient to establish an obligation to convey freehold ownership. The Court inferred that the landowners became promoters because they exercised control over construction […]
Read more
The Expanding Definition of “Promoter”: Impact on Landowners’ Rights. Need for parliamentary intervention?
NEED FOR AUTHORITATIVE CLARIFICATION BY THE BOMBAY HIGH COURT ON THE SCOPE OF SECTION 11 OF MOFA: GERALD MICHAEL MISQUITTA AND ROHINI GUPTA Gerald Michael Misquitta Vs State of Maharashtra ( “Gerald” ) Rohini Gupta & Anr. v. District Deputy Registrar, Co-operative Societies & Ors., WP No. 5991/2026, Bombay High Court, decided 8 September 2026, in which Mohini Gupta is the second petitioner. Indian Kanoon ( “Gupta” ) The two cases are quite closely connected because both concern Section 11 of MOFA, deemed conveyance, landowners/lessees, and the powers of the District Deputy Registrar (DDR). But there is an important difference: Gerald Misquitta is primarily a procedural/natural-justice case, whereas Gupta is substantially a Section 2(c)/Section 11 substantive-promoter case. Basic facts — side-by-side Sr No Particulars Gerald Michael Misquitta v. State of Maharashtra Rohini Gupta & Anr. v. DDR3 1 Court Bombay High Court Bombay High Court 2 Judgment date 25 Feb 2026 8 Sept 2026 3 Petition WP 1739/2022 WP 5991/2026 4 Ownership Misquitta family property, Vile Parle West Gupta family property, Juhu 5 Original owners Multiple Misquitta co-owners Late Kundanlal Laxmichand Gupta; petitioners were his heirs 6 Developer/lessee structure Owners → Rahejas → A.K. Associates/sub-lessee Owner → Raheja/Wadhwa lessees → developers 7 Society Name Priya Co-operative Housing Society Queens Park Premises Co-operative Society 8 Lease 98-year lease 98-year lease 9 Earlier transfer to society Society claimed/received only leasehold-related rights Society already received assignment of leasehold rights in 1978 10 DDR order 28 May 2014 23 June 2025 11 Main challenge Owners were not properly impleaded/heard; DDR did not conduct required enquiry Whether landowners themselves became “promoters” under MOFA Result DDR order + conveyance quashed and remanded Petition dismissed; DDR order upheld The Misquitta judgment records that the property was owned by several co-owners and that the society’s deemed-conveyance application proceeded without impleading all of them. Indian Kanoon The Gupta judgment records a 98-year lease from Kundanlal Gupta and subsequent construction of Queens Park by the lessees/developers. Indian Kanoon Paragraph-wise comparison This is the more useful way to read the judgments. Para 1–3 — What is being challenged? Gerald — paras 1–3 The petitioner challenged the DDR’s 28 May 2014 certificate permitting unilateral deemed conveyance and the subsequent registered deed of assignment/transfer dated 5 July 2014. The important factual feature was that the petitioner claimed to be a co-owner, but was not properly made a party to the deemed-conveyance proceedings. Indian Kanoon Gupta — paras 1–4 The petitioners were the legal heirs of the original landowner. They challenged the DDR’s order dated 23 June 2025 granting unilateral deemed conveyance of approximately 3,901.70 sq.m. to Queens Park Society. The Gupta petitioners said that their father had died in 1981 and that the DDR had proceeded on a notice issued in his name. Indian Kanoon Difference In Gerald, the central problem was: “Were all persons whose rights were affected actually heard?” In Gupta, the central question became: “Were these landowners themselves promoters under Section 2(c) MOFA?” Paragraphs 10–15 — Meaning of “promoter” This is the most important substantive difference. Gerald The Court did not finally determine the title/promoter controversy because […]
Read more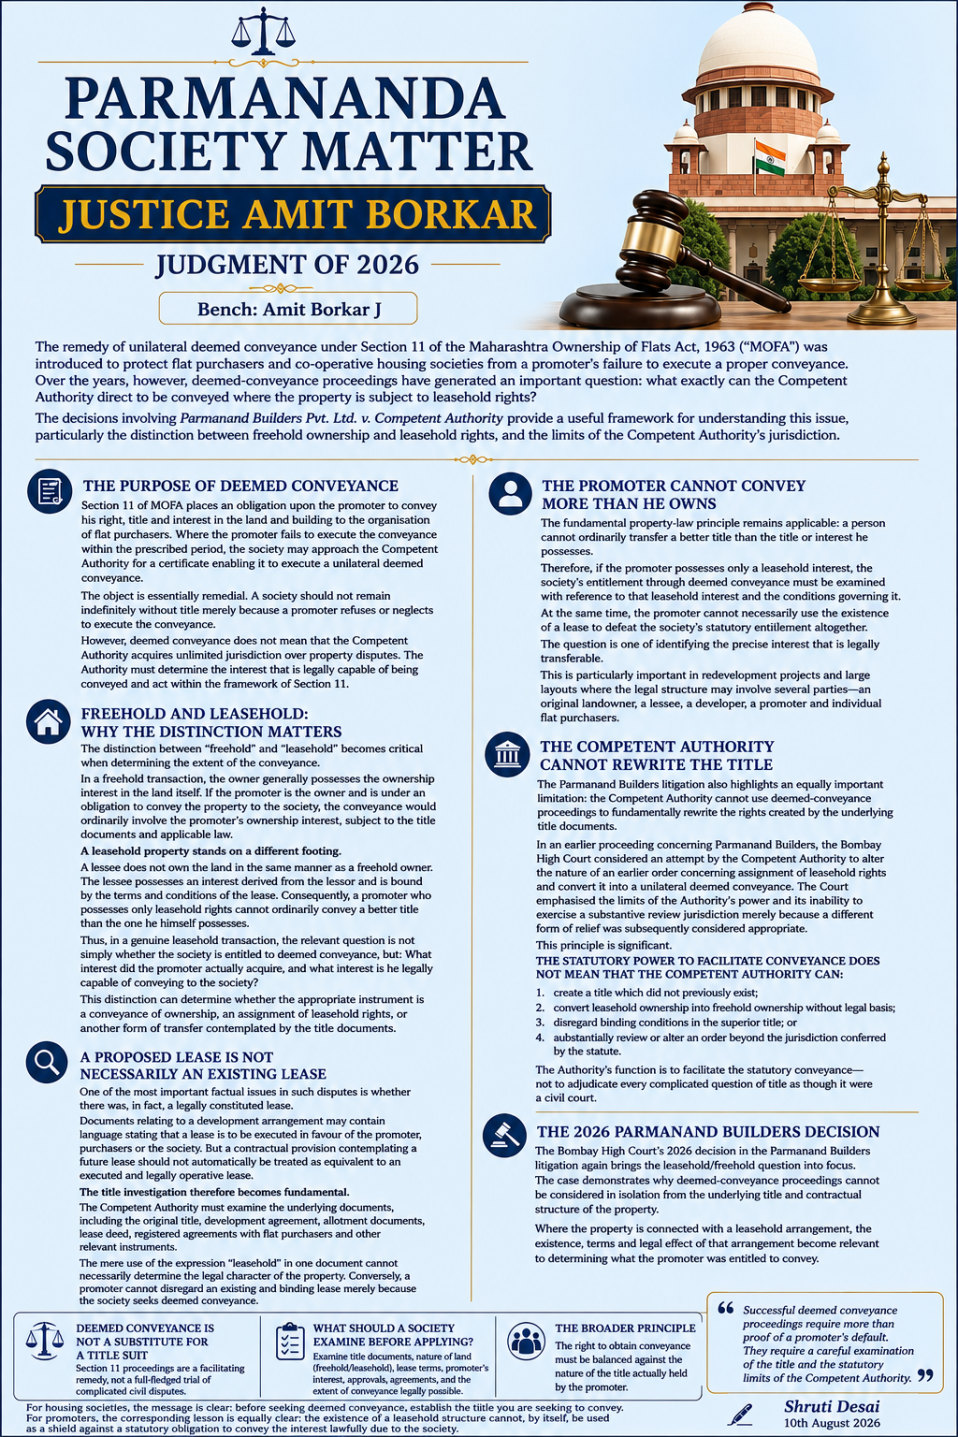
Unilateral Deemed Conveyance under MOFA: Leasehold, Freehold and the Limits of the Competent Authority Lessons from Parmanand Builders v. Competent Authority: 24 February, 2026
Bench: Amit Borkar J The remedy of unilateral deemed conveyance under Section 11 of the Maharashtra Ownership of Flats Act, 1963 (“MOFA”) was introduced to protect flat purchasers and co-operative housing societies from a promoter’s failure to execute a proper conveyance. Over the years, however, deemed-conveyance proceedings have generated an important question: what exactly can the Competent Authority direct to be conveyed where the property is subject to leasehold rights? The decisions involving Parmanand Builders Pvt. Ltd. v. Competent Authority provide a useful framework for understanding this issue, particularly the distinction between freehold ownership and leasehold rights, and the limits of the Competent Authority’s jurisdiction. The purpose of deemed conveyance Section 11 of MOFA places an obligation upon the promoter to convey his right, title and interest in the land and building to the organisation of flat purchasers. Where the promoter fails to execute the conveyance within the prescribed period, the society may approach the Competent Authority for a certificate enabling it to execute a unilateral deemed conveyance. The object is essentially remedial. A society should not remain indefinitely without title merely because a promoter refuses or neglects to execute the conveyance. However, deemed conveyance does not mean that the Competent Authority acquires unlimited jurisdiction over property disputes. The Authority must determine the interest that is legally capable of being conveyed and act within the framework of Section 11. Freehold and leasehold: why the distinction matters The distinction between “freehold” and “leasehold” becomes critical when determining the extent of the conveyance. In a freehold transaction, the owner generally possesses the ownership interest in the land itself. If the promoter is the owner and is under an obligation to convey the property to the society, the conveyance would ordinarily involve the promoter’s ownership interest, subject to the title documents and applicable law. A leasehold property stands on a different footing. A lessee does not own the land in the same manner as a freehold owner. The lessee possesses an interest derived from the lessor and is bound by the terms and conditions of the lease. Consequently, a promoter who possesses only leasehold rights cannot ordinarily convey a better title than the one he himself possesses. Thus, in a genuine leasehold transaction, the relevant question is not simply whether the society is entitled to deemed conveyance, but: What interest did the promoter actually acquire, and what interest is he legally capable of conveying to the society? This distinction can determine whether the appropriate instrument is a conveyance of ownership, an assignment of leasehold rights, or another form of transfer contemplated by the title documents. A proposed lease is not necessarily an existing lease ? One of the most important factual issues in such disputes is whether there was, in fact, a legally constituted lease. Documents relating to a development arrangement may contain language stating that a lease is to be executed in favour of the promoter, purchasers or the society. But a contractual provision contemplating a future lease should not automatically be treated as equivalent to an executed and legally operative lease. The title investigation therefore becomes fundamental. The Competent Authority must […]
Read more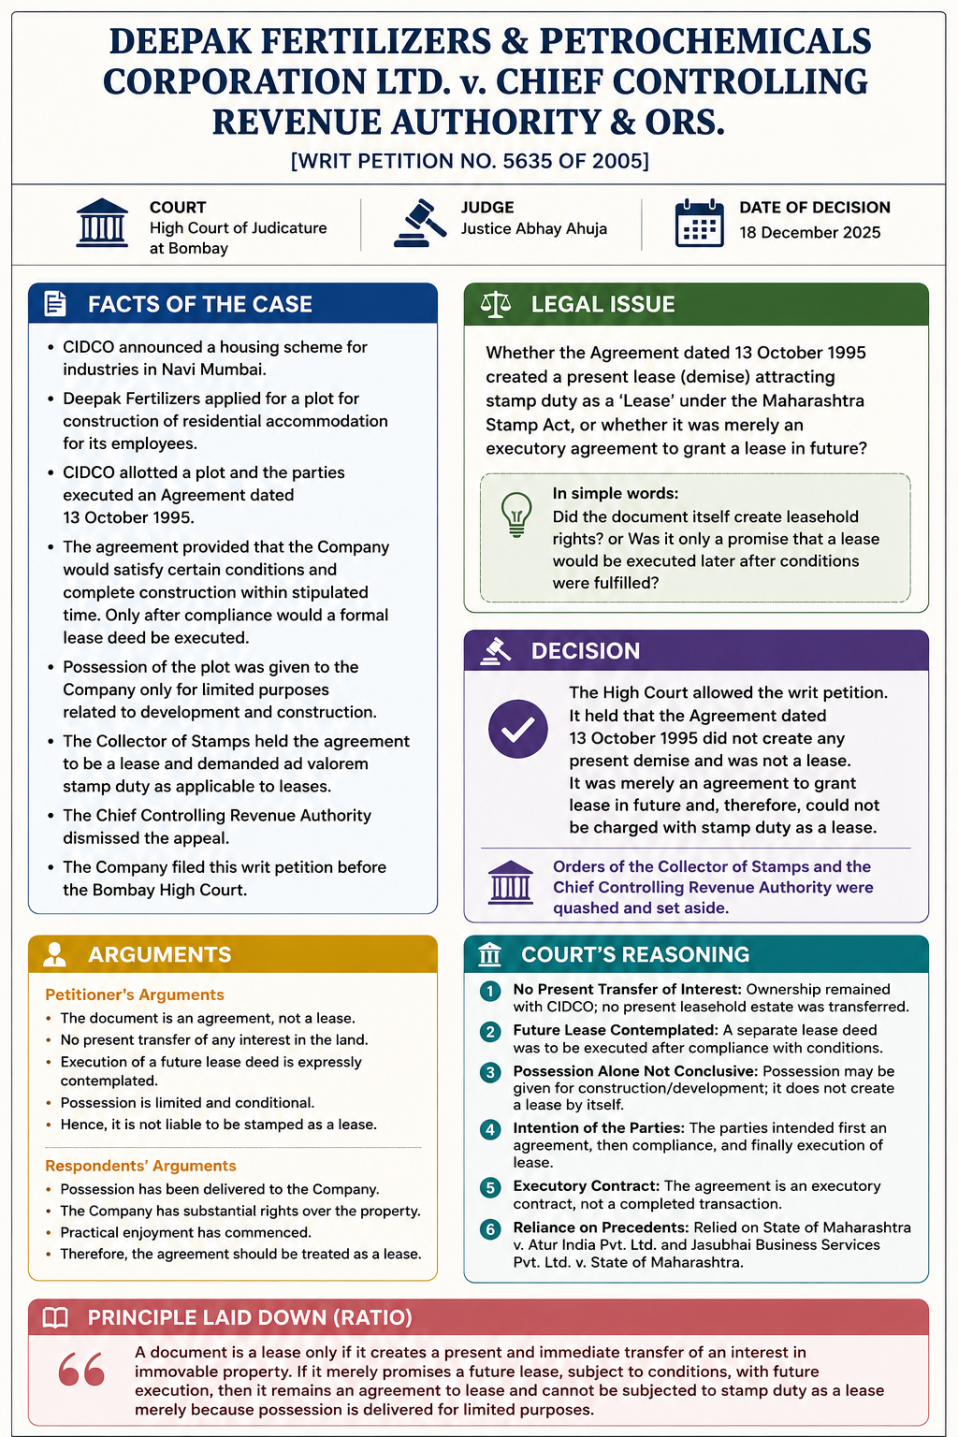
Lease or Agreement to Lease? A Case Analysis of Deepak Fertilizers v. Chief Controlling Revenue Authority
Deepak Fertilizers and Petrochemicals Corporation Ltd. v. Chief Controlling Revenue Authority & Ors., Writ Petition No. 5635 of 2005, decided on 18 December 2025 by Justice Abhay Ahuja. (Verdictum) Background and Facts The dispute arose from an agreement executed on 13 October 1995 between Deepak Fertilizers and CIDCO under a scheme through which CIDCO allotted developed residential plots to industries for construction of staff housing. The material facts were: CIDCO announced a housing scheme for industries in Navi Mumbai. Deepak Fertilizers applied for a plot for construction of residential accommodation for its employees. CIDCO allotted a plot and the parties executed an Agreement dated 13 October 1995. The agreement contemplated that: the company would satisfy several conditions; construction had to be completed within stipulated time; only after compliance would a formal lease deed be executed. Possession given to the company was only for limited purposes connected with development and construction under the agreement. The Collector of Stamps held that the agreement itself amounted to a lease and demanded ad valorem stamp duty as applicable to leases. The Chief Controlling Revenue Authority dismissed the company’s appeal. Deepak Fertilizers challenged those orders before the Bombay High Court. (Verdictum) Procedural History Authority Decision Collector of Stamps Held the agreement was a lease and liable to stamp duty as a lease Chief Controlling Revenue Authority Confirmed Collector’s order Bombay High Court Allowed the writ petition and set aside both orders Legal Issue The central legal issue was: Whether the Agreement dated 13 October 1995 created a present lease (demise) attracting stamp duty as a “Lease” under the Maharashtra Stamp Act, or whether it was merely an executory agreement to grant a lease in future. In simple words: Did the document itself create leasehold rights? or Was it only a promise that a lease would be executed later after conditions were fulfilled? Petitioner’s Arguments Deepak Fertilizers argued that: the document repeatedly described itself as an Agreement; it did not transfer any present interest in land; no leasehold estate came into existence immediately; execution of a future lease deed was expressly contemplated; possession was limited and conditional; therefore the agreement could not be stamped as a lease. The company relied upon earlier Bombay High Court decisions distinguishing between: agreement to lease actual lease Respondents’ Arguments The Revenue and CIDCO contended that: possession had already been handed over; the company had substantial rights over the property; practical enjoyment had commenced; therefore the agreement should be treated as a lease for stamp purposes. Core Legal Question Considered by the Court The Court examined a classical property law distinction: Does the document itself create a present demise? If yes → it is a lease. If no → it is merely an agreement to lease. This distinction has existed in Indian property law for decades. Court’s Reasoning Justice Abhay Ahuja analysed the document clause-by-clause. The Court emphasized that the substance of the document—not merely possession or nomenclature—determines its legal character. (Verdictum) No Present Transfer of Interest The Court observed that: ownership remained with CIDCO; no present leasehold estate was transferred; the agreement only created contractual obligations. This is the most important […]
Read more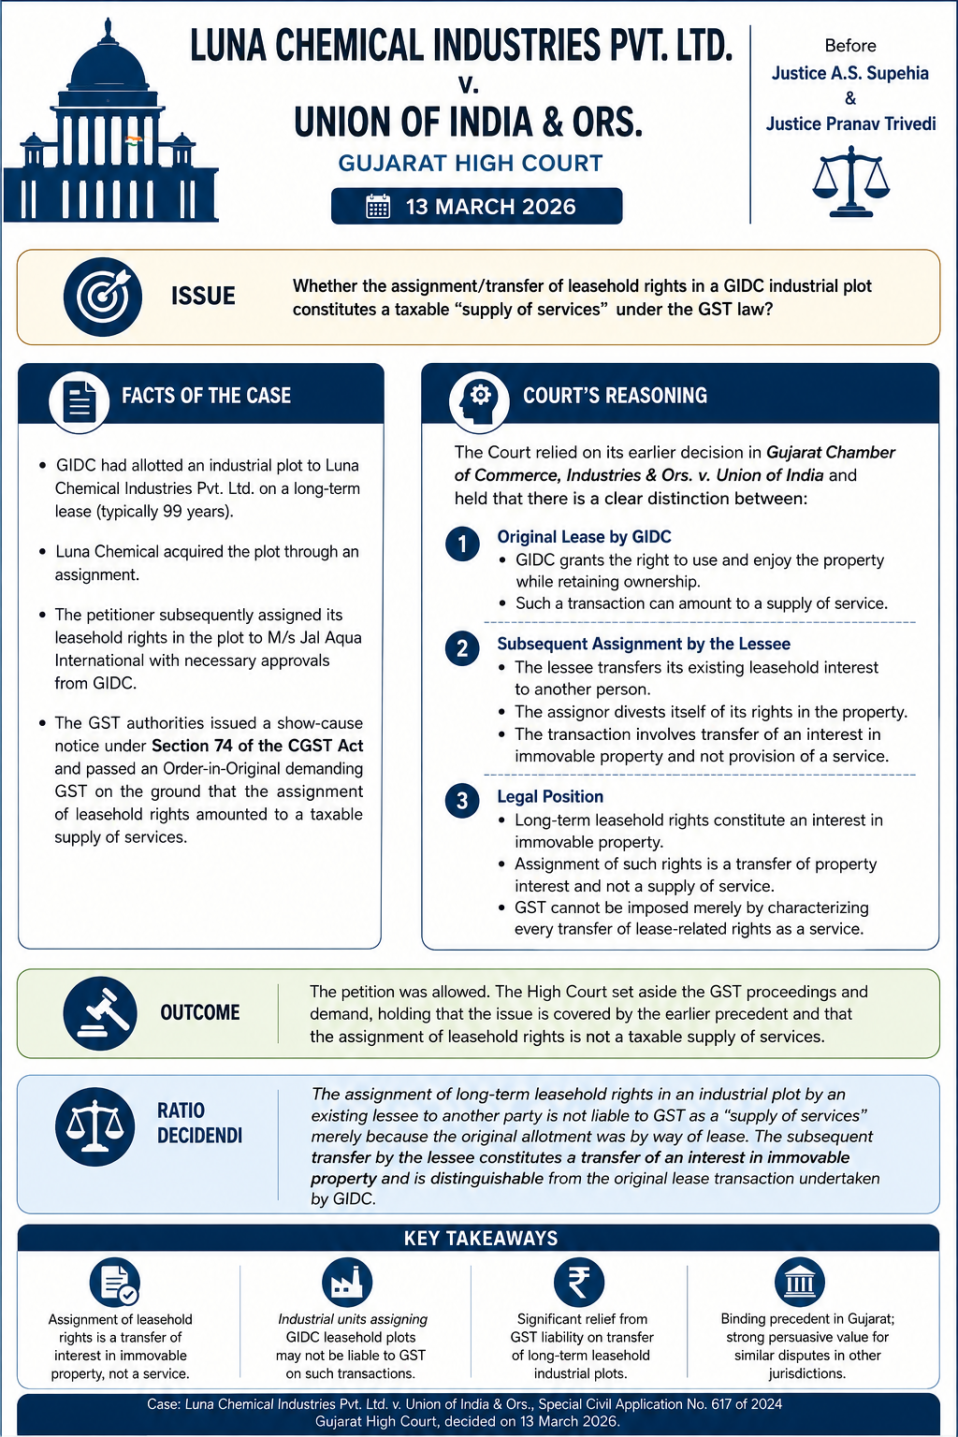
ASSIGNMENT OF LEASEHOLD RIGHTS UNDER GST: ANALYSIS OF LUNA CHEMICAL INDUSTRIES PVT. LTD. V. UNION OF INDIA (GUJARAT HIGH COURT)
Introduction The Gujarat High Court’s decision in Luna Chemical Industries Pvt. Ltd. v. Union of India has added another significant chapter to the ongoing debate concerning the GST implications of transfers of leasehold rights in industrial plots. The judgment reaffirms the principle that a transfer of leasehold rights by an existing lessee is fundamentally different from the original grant of lease by a statutory authority and cannot automatically be subjected to GST as a supply of service. The ruling is particularly relevant for industries operating in Gujarat Industrial Development Corporation (GIDC) estates and for taxpayers involved in the transfer of long-term leasehold interests in industrial land. Background of the Dispute Luna Chemical Industries Pvt. Ltd. held leasehold rights in an industrial plot allotted through the GIDC framework. Subsequently, the company assigned its leasehold rights to another entity after obtaining the requisite approvals from GIDC. The GST authorities initiated proceedings under Section 74 of the Central Goods and Services Tax Act, 2017, alleging that the assignment of leasehold rights constituted a taxable supply of services and consequently raised a demand for GST. The petitioner challenged the demand before the Gujarat High Court. CORE LEGAL ISSUE The principal question before the Court was: Whether the assignment of leasehold rights in an industrial plot by a lessee to a third party constitutes a taxable supply of services under the GST regime. The answer depended upon the characterization of the transaction. If the transaction represented a supply of service, GST would be leviable. Conversely, if it constituted a transfer of an interest in immovable property, it would fall outside the scope of taxable supplies. RATIO DECIDENDI The Court held that the transfer of leasehold rights by an existing lessee is legally distinct from the original lease granted by GIDC. The ratio of the decision may be summarized as follows: The assignment of long-term leasehold rights by a lessee results in the transfer of an existing interest in immovable property and does not amount to a taxable supply of services merely because the original allotment was made through a lease arrangement. Consequently, GST cannot be imposed on such assignment solely by treating it as a continuation of the original leasing transaction. Distinction between Lease and Assignment A key aspect of the judgment is the Court’s recognition of the legal distinction between: Original Lease by GIDC GIDC grants the right to use and enjoy immovable property while retaining ownership. Such a transaction may be characterized as a supply of service under GST. Subsequent Assignment by the Lessee The lessee transfers its existing leasehold interest to another person. The assignor divests itself of the rights held in the property. The transaction involves transfer of an interest in immovable property rather than provision of a service. The Court emphasized that these are two separate legal transactions and cannot be treated identically for GST purposes. Reliance on Earlier Precedent The judgment follows the Gujarat High Court’s earlier ruling in Gujarat Chamber of Commerce & Industry v. Union of India, where the Court had examined the GST treatment of leasehold interests in industrial plots. By relying on the principles laid […]
Read more